Black-Litterman
Install and import#
npm install fintech-algorithmsimport { blackLittermanAllocate } from "fintech-algorithms/portfolio-construction/bayesian-and-robust-allocation/black-litterman";Signature#
blackLittermanAllocate(input)Combines market-implied equilibrium returns with stated views and their confidence, producing the posterior expected returns an optimizer then uses.
Parameters#
| Name | Type | Notes |
|---|---|---|
input | BlackLittermanInput |
Worked example#
executed Captured by running this function on the input its own test provides. Real output of real code — but not asserted against a published figure.
Input#
{
  "marketWeights": [0.5, 0.5],
  "covariance": [
    [0.04, 0],
    [0, 0.01]
  ],
  "riskAversion": 2,
  "tau": 0.5,
  "viewMatrix": [
    [1, -1]
  ],
  "viewReturns": [0.04],
  "viewErrorCovariance": [
    [0.0025]
  ],
  "riskPenalty": 1
}Call#
blackLittermanAllocate(input)Returns#
object with 9 fields: priorReturns, posteriorReturns, weights, priorView, posteriorView, viewSurprise, variance, objective, …
{
  "priorReturns": [0.04, 0.01],
  "posteriorReturns": [0.04727272727272727, 0.008181818181818182],
  "weights": [0.5909090909090909, 0.4090909090909091],
  "priorView": [0.03],
  "posteriorView": [0.03909090909090909],
  "viewSurprise": [0.010000000000000002],
  "variance": 0.015640495867768597,
  "objective": 0.015640495867768597,
  "status": "optimal"
}Diagrams#
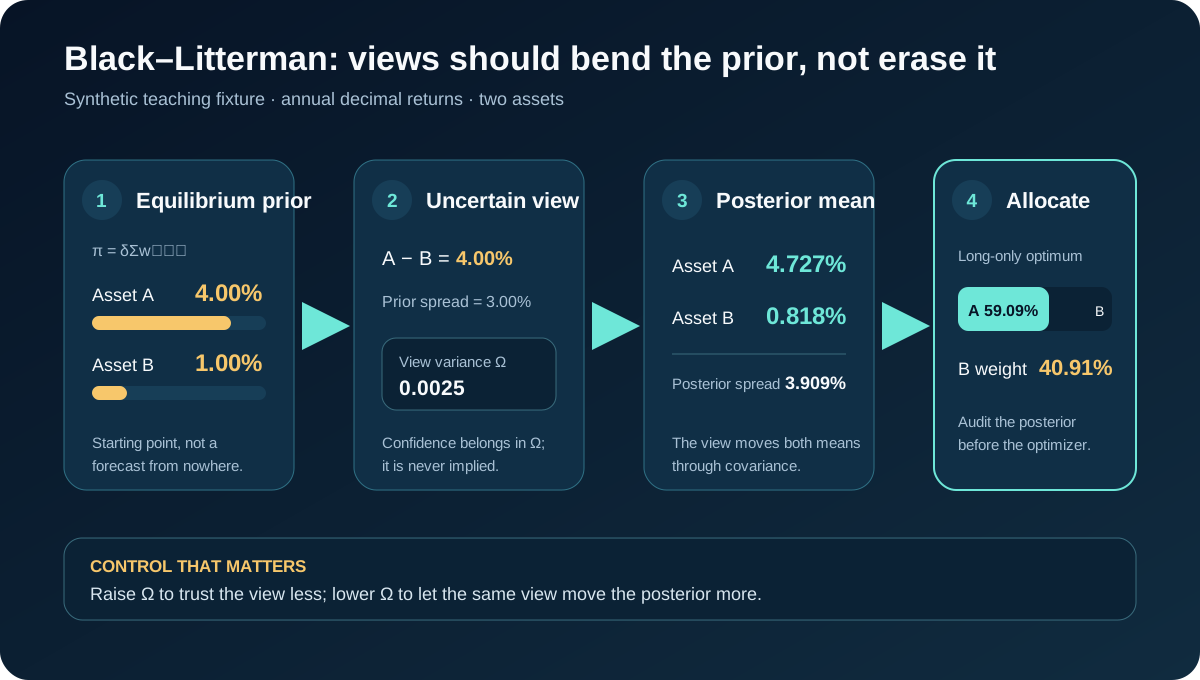
Calculation flow#
Diagram
flowchart TB
    N0[Validate inputs] --> N1
    N1[Derive market prior] --> N2
    N2[Compute view surprise] --> N3
    N3[Update the mean] --> N4
    N4[Allocate and check]
How it works#
This page states the contract — how to call it correctly. The article explains the concept: why it works, and where it breaks.
References#
- Global Portfolio Optimization — Fischer Black and Robert Litterman.
- Estimation error and Bayesian allocation — MOSEK ApS.