Global Minimum Variance
Install and import#
npm install fintech-algorithmsimport { globalMinimumVariance } from "fintech-algorithms/portfolio-construction/mean-risk-optimization/global-minimum-variance";Signature#
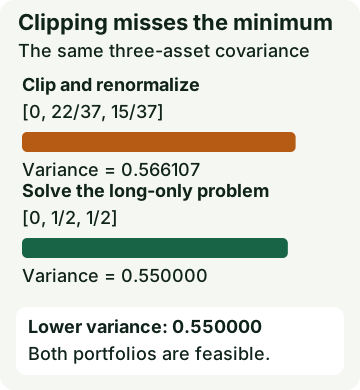
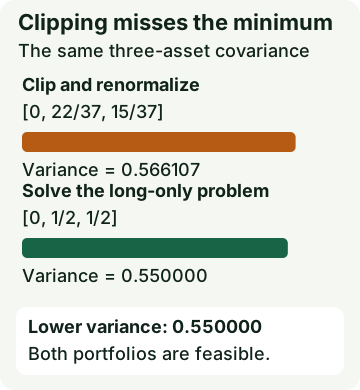
globalMinimumVariance(assetIdsInput, covarianceInput, options)Computes the lowest-variance weights obtainable from a covariance matrix alone, with no expected-return input, and shows why clipping a short weight is not optimization.
Parameters#
| Name | Type | Notes |
|---|---|---|
assetIdsInput | unknown | |
covarianceInput | unknown | |
options | GMVOptions | optional |
Worked example#
executed Captured by running this function on the input its own test provides. Real output of real code — but not asserted against a published figure.
Input#
["A", "B"][
[0.04, 0.01],
[0.01, 0.09]
]{
"maxIterations": 10000
}Call#
globalMinimumVariance(assetIdsInput, covarianceInput, options)Returns#
object with 19 fields: assetIds, mu, matrixScale, variant, method, maxIterations, weights, variance, …
{
  "assetIds": ["A", "B"],
  "mu": null,
  "matrixScale": 0.09,
  "variant": "gmv-long-only-fully-invested",
  "method": "projected-gradient-simplex-line-search",
  "maxIterations": 10000,
  "weights": [0.7272727272727273, 0.27272727272727276],
  "variance": 0.03181818181818182,
  "volatility": 0.17837651700316895,
  "expectedReturn": null,
  "budgetResidual": 0,
  "lowerBoundResidual": 0,
  "fwGapS": 0,
  "fwGap": 0
}
Showing 14 of 19 fields.
Diagrams#
How it works#
This page states the contract — how to call it correctly. The article explains the concept: why it works, and where it breaks.
References#
- MOSEK Portfolio Optimization Cookbook — Markowitz portfolio
- On the Estimation of the Global Minimum Variance Portfolio
- Portfolio Optimization / Markowitz model
- SEC: Stock Splits
- Investor.gov: Ex-Dividend Dates
- UW Markowitz project notes
- Historical/case boundary
- 2026-09-16